Inflation Is Back at 3.7%: Which Costs Are Rising Fastest?
US consumer prices rose 3.7% in the year to September 2026, and gasoline (+34.2%) and airline fares (+22.4%) are rising fastest. Core inflation, which strips out food and energy, is only 2.6%, so this is mainly an energy shock rather than a broad 2022-style surge. Wages grew 3.0%, meaning real hourly pay fell 0.7%. KalQLater estimates the price rises add about $2,570 a year to a typical household’s spending.
The short answer: inflation is back above 3%, but it is mostly gasoline
Inflation is genuinely back up: 3.7% in September 2026, versus 2.4% as recently as February. But the rise is concentrated. Energy is up 20.4% while core prices are up 2.6%, the slowest core pace in our 2024 to 2026 series. This is not a return to 2022, when headline inflation peaked at 9.1%.
The Bureau of Labor Statistics reported on 14 October 2026 that the Consumer Price Index for all urban consumers rose 0.6% in September alone and 3.7% over 12 months. That is up from 3.4% in August. BLS said the 9.1% monthly jump in gasoline accounted for over half of the monthly increase.
The rest of the basket tells a calmer story. Food rose 2.5% over the year, groceries just 1.8%, and shelter 3.2%. Used cars got cheaper (-1.5%), and so did car insurance (-5.0%), which was one of the big villains of the last inflation wave.
Our verdict on the trend: the headline is real and households are feeling it, especially drivers and anyone flying. The popular claim that inflation is "back to 2022 levels" is false on every measure we checked. Whether it comes down depends largely on oil, and the US Energy Information Administration expects crude to stay high through the end of 2026.
Which prices are rising fastest in 2026?
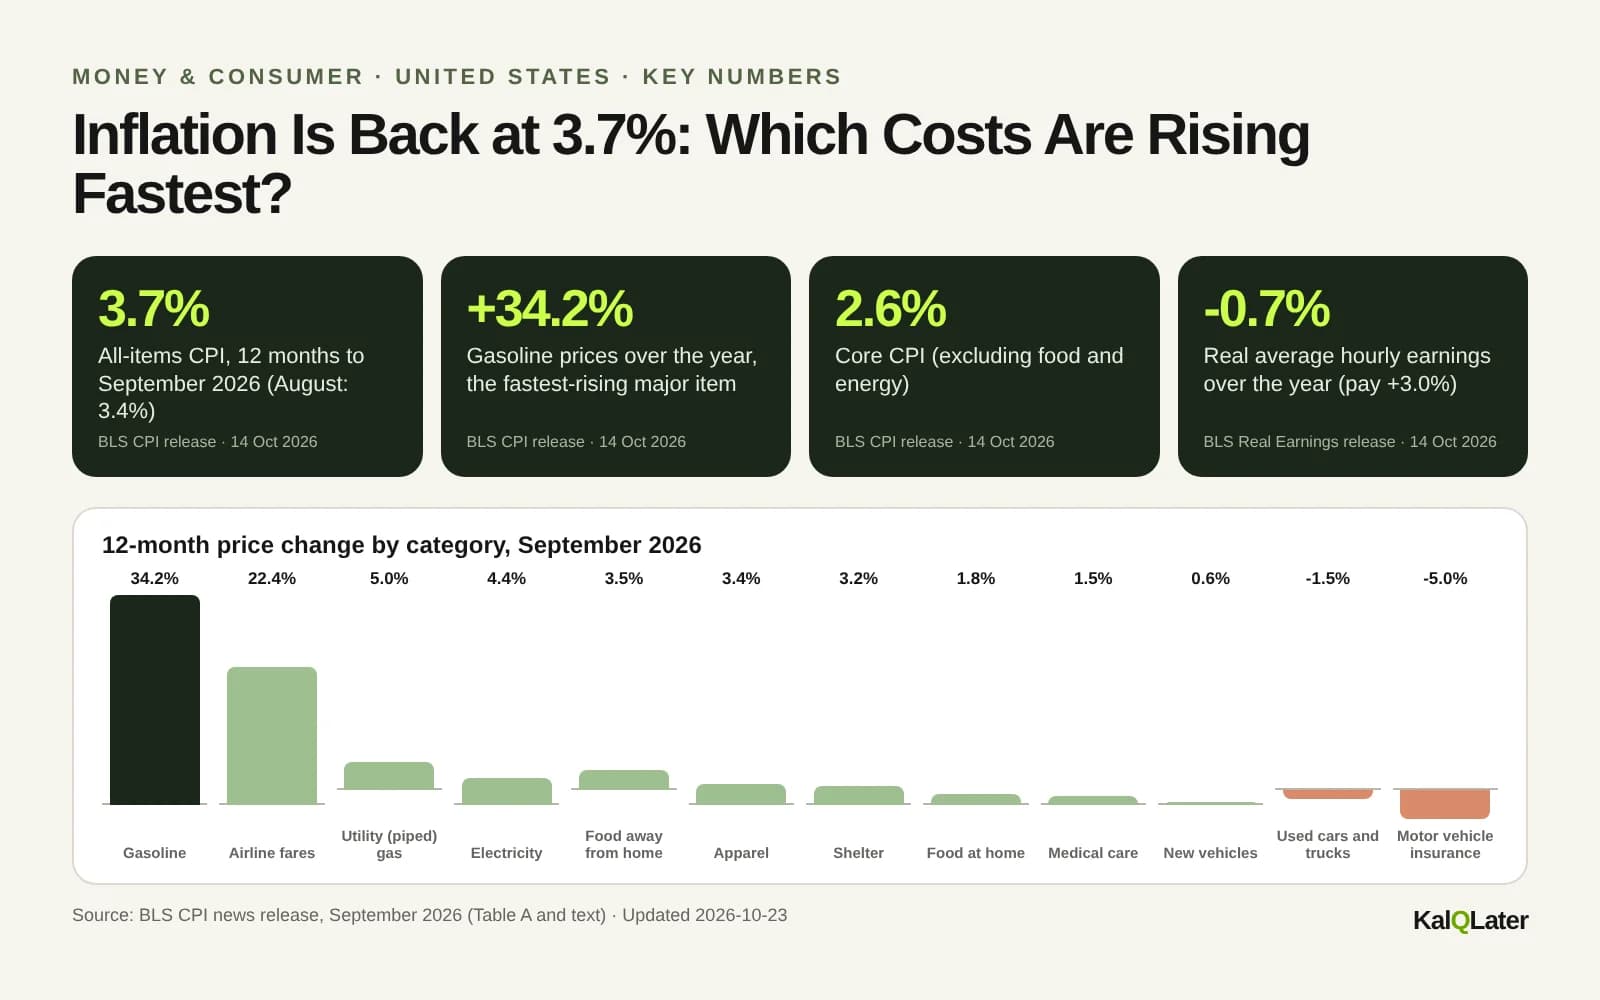
Gasoline is up 34.2% over the year, airline fares 22.4% and the overall energy index 20.4%. After those, the next fastest are utility gas (5.0%), electricity (4.4%), restaurant meals (3.5%) and apparel (3.4%). Several big items are actually falling, including used cars and car insurance.
12-month price change by category, September 2026
Source: BLS CPI news release, September 2026 (Table A and text)View the data
| Label | Value |
|---|---|
| Gasoline | 34.2% |
| Airline fares | 22.4% |
| Utility (piped) gas | 5.0% |
| Electricity | 4.4% |
| Food away from home | 3.5% |
| Apparel | 3.4% |
| Shelter | 3.2% |
| Food at home | 1.8% |
| Medical care | 1.5% |
| New vehicles | 0.6% |
| Used cars and trucks | -1.5% |
| Motor vehicle insurance | -5.0% |
Fast-rising does not always mean costly. Gasoline carries a relative importance of about 3.9% in the CPI basket, so a 34% rise matters a lot. Airline fares are a much smaller slice of most budgets. Shelter, by contrast, rises only 3.2% but makes up 35.3% of the index, so it still adds about a point to headline inflation on its own.
Using BLS relative-importance weights, KalQLater estimates that energy contributed roughly 1.3 percentage points of the 3.7%, gasoline alone about 1.0 point, core items about 2.0 points and food about 0.3 points. These are approximations (see methodology), but they show why the headline jumped while most prices did not.
Is inflation going up again? The 2024 to 2026 path
Yes, compared with early 2026: headline CPI rose from 2.4% in January and February to 3.7% in September. It is not a straight line up, though. Inflation spiked to 4.3% in May 2026 when gasoline surged, eased to 3.4% by July and August, then climbed again in September.
Headline CPI, 12-month % change, Jan 2024 to Sep 2026
Source: BLS CPI-U (CPIAUCNS) via FRED; KalQLater calculationView the data
| Label | Value |
|---|---|
| Jan 24 | 3.1% |
| Feb 24 | 3.2% |
| Mar 24 | 3.5% |
| Apr 24 | 3.4% |
| May 24 | 3.3% |
| Jun 24 | 3.0% |
| Jul 24 | 2.9% |
| Aug 24 | 2.5% |
| Sep 24 | 2.4% |
| Oct 24 | 2.6% |
| Nov 24 | 2.7% |
| Dec 24 | 2.9% |
| Jan 25 | 3.0% |
| Feb 25 | 2.8% |
| Mar 25 | 2.4% |
| Apr 25 | 2.3% |
| May 25 | 2.4% |
| Jun 25 | 2.7% |
| Jul 25 | 2.7% |
| Aug 25 | 2.9% |
| Sep 25 | 3.0% |
| Nov 25 | 2.7% |
| Dec 25 | 2.7% |
| Jan 26 | 2.4% |
| Feb 26 | 2.4% |
| Mar 26 | 3.3% |
| Apr 26 | 3.8% |
| May 26 | 4.3% |
| Jun 26 | 3.5% |
| Jul 26 | 3.4% |
| Aug 26 | 3.4% |
| Sep 26 | 3.7% |
The jump in March 2026 is the clearest break. The seasonally adjusted CPI rose 0.9% that month, driven by a 21.2% one-month rise in gasoline, according to the BLS table of monthly changes. Gasoline then fell 9.7% in June, which is why inflation briefly cooled, before rising 3.9% in August and 9.1% in September.
That stop-start pattern is what an oil shock looks like. The EIA’s October Short-Term Energy Outlook links it to constrained oil flows from the Middle East, convoys through the Strait of Hormuz and attacks on Saudi Arabia’s East-West pipeline. US retail gasoline averaged $4.35 a gallon in September, per EIA. For the pump-price detail, see our gas prices and the midterms report.
Core inflation 2026: why the 2.6% figure matters more
Core CPI rose 2.6% over the year to September 2026, roughly unchanged since January (2.5%). Core leaves out volatile food and energy and is the better guide to where inflation settles once an oil shock fades. On that measure, inflation is closer to the Fed’s target than at any time in 2024 or 2025.
Core CPI (ex food and energy), 12-month % change, Jan 2024 to Sep 2026
Source: BLS CPI-U less food and energy (CPILFENS) via FRED; KalQLater calculationView the data
| Label | Value |
|---|---|
| Jan 24 | 3.9% |
| Feb 24 | 3.8% |
| Mar 24 | 3.8% |
| Apr 24 | 3.6% |
| May 24 | 3.4% |
| Jun 24 | 3.3% |
| Jul 24 | 3.2% |
| Aug 24 | 3.2% |
| Sep 24 | 3.3% |
| Oct 24 | 3.3% |
| Nov 24 | 3.3% |
| Dec 24 | 3.2% |
| Jan 25 | 3.3% |
| Feb 25 | 3.1% |
| Mar 25 | 2.8% |
| Apr 25 | 2.8% |
| May 25 | 2.8% |
| Jun 25 | 2.9% |
| Jul 25 | 3.1% |
| Aug 25 | 3.1% |
| Sep 25 | 3.0% |
| Nov 25 | 2.6% |
| Dec 25 | 2.6% |
| Jan 26 | 2.5% |
| Feb 26 | 2.5% |
| Mar 26 | 2.6% |
| Apr 26 | 2.8% |
| May 26 | 2.9% |
| Jun 26 | 2.6% |
| Jul 26 | 2.5% |
| Aug 26 | 2.5% |
| Sep 26 | 2.6% |
For most of 2024 and 2025, core inflation ran above headline because housing and services were sticky while energy was cheap. In 2026 that flipped. Since March, headline has run 0.7 to 1.4 points above core, which is the signature of an energy shock rather than an economy-wide overheating.
There is a catch. Core goods and services are not immune to fuel costs. Airline fares (+22.4%) sit inside core services and are clearly passing on jet fuel. Transportation services rose 0.6% in September alone. If energy stays high for months, more of it seeps into core prices through delivery, travel and restaurant costs.
Is inflation back to 2022 levels?
No. Headline inflation peaked at 9.1% in June 2022; today it is 3.7%, well under half that. Core inflation peaked at 6.6% in September 2022 versus 2.6% now. The one thing that does rhyme with 2022 is gasoline, which again is driving the headline number.
| Measure | 2022 peak | September 2026 | Gap |
|---|---|---|---|
| Headline CPI, 12-month | 9.1% (June 2022) | 3.7% | -5.4 points |
| Core CPI, 12-month | 6.6% (September 2022) | 2.6% | -4.0 points |
| Headline CPI, same month (September) | 8.2% (September 2022) | 3.7% | -4.5 points |
We calculated the 2022 figures from the same BLS index series used in our charts: June 2022 CPI of 296.311 against 271.696 a year earlier gives 9.06%, which BLS reported as 9.1%. September 2022 core of 298.442 against 279.884 gives 6.6%.
The structural difference is breadth. In 2022, rents, cars, food and services were all rising quickly at the same time. In 2026, groceries are up 1.8%, cars are flat to falling and core is near 2.5%. That is one reason the Fed’s September 2026 move was a single quarter-point increase, to 3.75%–4.00%.
What does 3.7% inflation cost a typical household? Your personal inflation rate
At September’s price changes, a typical US household’s spending basket costs about $2,570 more a year, or roughly $214 a month. Gasoline alone accounts for about a third of that extra cost. Your own number depends mostly on how much you drive and fly: a heavy driver’s personal inflation is close to 5%, a non-driver’s under 3%.
Headline CPI is an average. To make it personal, we took the average annual spending of US households from the BLS Consumer Expenditure Survey (2024, released December 2025) and applied the matching September 2026 CPI change to each category. We left out personal insurance and pensions and cash contributions, which are not consumer prices.
| Spending category | Annual spending (CE 2024) | CPI change used | Extra cost per year |
|---|---|---|---|
| Shelter | $16,317 | +3.2% (shelter) | $522 |
| Gasoline | $2,411 | +34.2% (gasoline) | $825 |
| Utilities, fuels and public services | $4,736 | +4.6% (energy services) | $218 |
| Food at home | $6,224 | +1.8% | $112 |
| Food away from home | $3,945 | +3.5% | $138 |
| Public and other transportation | $1,131 | +22.4% (airline fares) | $253 |
| Healthcare | $6,197 | +1.5% (medical care) | $93 |
| Apparel and services | $2,001 | +3.4% | $68 |
| Vehicle purchases | $5,337 | +0.6% (new vehicles) | $32 |
| Vehicle insurance | $1,993 | -5.0% | -$100 |
| Everything else (entertainment, household, education, personal care, etc.) | $15,794 | +2.6% (core CPI) | $411 |
| Total | $66,086 | 3.9% weighted | $2,572 |
The weighted result, 3.9%, is slightly above the official 3.7% because the CE budget gives gasoline and airfare a bigger combined share than the CPI weights do. Gasoline contributes 32% of the extra cost, shelter 20% and airfare 10%. Groceries, despite the headlines, account for only about 4%.
| Household | Assumption | Extra cost per year | Personal inflation rate |
|---|---|---|---|
| Typical household | CE 2024 average budget | $2,572 | 3.9% |
| Heavy driver | Double the average gasoline spend ($4,822) | $3,397 | 5.0% |
| Non-driver | No gasoline spending | $1,747 | 2.7% |
Are wages keeping up with inflation in 2026?
No, not since spring. Average hourly earnings rose 3.0% in the year to September 2026 while prices rose 3.7%, so real hourly pay fell 0.7%. In January, wages were beating inflation by about 1.3 points. The squeeze came almost entirely from the gasoline spike, not from slower pay growth alone.
Real wage growth: hourly pay growth minus CPI inflation, 2026 (percentage points)
Source: BLS average hourly earnings (CES0500000003) and CPI-U via FRED; KalQLater calculationView the data
| Label | Value |
|---|---|
| Jan | 1.3 pts |
| Feb | 1.3 pts |
| Mar | 0.2 pts |
| Apr | -0.2 pts |
| May | -0.9 pts |
| Jun | -0.2 pts |
| Jul | -0.2 pts |
| Aug | -0.3 pts |
| Sep | -0.7 pts |
The BLS Real Earnings release confirms the September picture: real average hourly earnings fell 0.5% in the month and 0.7% over the year. Production and nonsupervisory workers, measured against CPI-W, lost 0.6% over the year. Because the workweek lengthened slightly, real weekly earnings fell by a smaller 0.1%.
Pay growth itself is slowing too. Hourly earnings growth eased from 3.85% in September 2025 to 3.0% in September 2026, and the September jobs report showed only 29,000 jobs added with unemployment at 4.2%. A cooling labor market makes it harder for workers to win raises that catch up.
In dollar terms: a worker earning $50,000 who got the average 3.0% raise received $1,500. Keeping pace with 3.7% inflation would have needed $1,850, leaving them about $350 a year worse off in purchasing power.
Why consumer sentiment hit a five-month low
The University of Michigan’s preliminary October 2026 sentiment index fell to 46.3, its lowest since May, from 48.1 in September. Shoppers expect 4.7% inflation over the next year, above the actual 3.7%, and 38% of Americans tell NerdWallet they expect to rely on credit for some expenses.
The Surveys of Consumers director Joanne Hsu said year-ahead and long-run inflation expectations rose for the second straight month to their highest readings since May. Long-run expectations are 3.5%. The current-conditions index hit 44.7, which Trading Economics described as an all-time low. The final October reading is due 23 October 2026; this article uses the preliminary figure.
NerdWallet’s Consumer Financial Resilience Index, based on a Harris Poll survey of 2,020 adults on 6 to 8 October, scored 61.6 out of 100 in October. The share expecting to rely on credit rose to 38% from 35% in September, and to 54% among parents of children under 18. Only 39% of households earning under $50,000 said they could cover a surprise $1,000 expense.
Will prices come down? October nowcast, oil and the Fed
Not quickly. The Cleveland Fed’s nowcast puts October 2026 CPI inflation at about 3.75%, essentially unchanged, and the EIA expects Brent crude to average $105 a barrel in the fourth quarter. Falling prices outright are unlikely outside gasoline; what most forecasters expect is slower increases if oil eases in 2027.
- October CPI nowcast: 3.75% The Cleveland Fed’s inflation nowcast (updated 23 October) has headline CPI up 0.25% in October and 3.75% over the year, with core at 2.48%. A nowcast is a model estimate, not data; BLS publishes the real figure on 10 November.
- Oil: elevated through year-end The EIA October STEO raised its Brent forecast to $96 a barrel for 2026 and $84 for 2027, and expects retail gasoline to average $3.91 a gallon in 2026 and $3.56 in 2027. Lower 2027 gas prices would pull headline inflation down sharply.
- The Fed: meeting 27 and 28 October In September the FOMC raised its target range by a quarter point to 3.75%–4.00%, voting 12-0 and saying inflation "remains elevated". Markets will watch whether it hikes again. See our Fed rate decision October 2026 analysis.
The Cleveland Fed’s model also points to fourth-quarter CPI rising at a 5.13% annualized rate, a reminder that the energy shock has not finished passing through. If oil follows the EIA path and drops in 2027, the year-on-year rate could fall quickly once the 2026 spikes drop out of the comparison. If the Middle East disruption worsens, it will not.
What 3.7% inflation means for Social Security, savings and borrowing
Social Security recipients get a 3.6% COLA in 2027, just under the 3.7% CPI-U and the 3.9% CPI-W. Savers need a yield above about 3.7% just to stand still in real terms. Borrowers face a Fed that is raising, not cutting, rates.
- 2027 COLA of 3.6% roughly matches, but does not beat, current inflation
- Retirees who drive little may come out ahead; heavy drivers will fall behind
- Model your raise with our Social Security COLA 2027 calculator
- Any account yielding under 3.7% is losing purchasing power before tax
- With the fed funds range at 3.75%–4.00%, the best high-yield savings and Treasury bills track the policy rate
- Cash in a checking account earning near zero loses about $37 per $1,000 a year at this rate
- The Fed raised rates in September 2026, so variable-rate debt got dearer
- Fixed-rate debt taken out earlier becomes cheaper in real terms as inflation runs
- Paying down card balances beats most savings yields
The COLA uses the CPI-W, which tracks working households and weights transport more heavily. That is why the CPI-W rose 3.9% while the CPI-U rose 3.7%. Our COLA 2027 report explains how Medicare Part B premiums claw back part of the raise.
What should you do about rising prices?
Focus on the categories actually driving your personal inflation: fuel, travel and energy bills. Groceries and car insurance are not where the 2026 squeeze is, so the biggest wins come from cutting gasoline use, booking flights early, and making sure your cash earns at least the inflation rate.
- 1Work out your own rate
Use the table above: your annual gas bill times 0.342 plus about 3% of other spending. If it is well above 3.7%, fuel is your lever.
- 2Cut fuel where it is cheap to do so
Combine trips, check tire pressure and compare station prices. Every $1,000 of yearly gas spending now costs about $342 more than a year ago.
- 3Book travel early and flexibly
Airfares are up 22.4%. Flexible dates and early booking matter more than usual; see our Thanksgiving flights 2026 analysis.
- 4Shop your car insurance renewal
Motor vehicle insurance prices fell 5.0% over the year, so a renewal quote that is going up is worth challenging.
- 5Move idle cash
Compare savings and Treasury bill yields against 3.7%. Anything below that loses value in real terms.
- 6Avoid locking in fuel-driven costs on credit
If you are relying on cards to cover the gap, prioritize paying them down before the Fed raises rates further.
Claims vs evidence
“Inflation is back to 2022 levels.”
3.7% headline vs the 9.1% June 2022 peak; core 2.6% vs 6.6% in September 2022.
False“Inflation is rising again.”
Headline CPI rose from 2.4% in February 2026 to 3.7% in September, and August to September rose 0.3 points.
True“Prices will come down soon.”
The Cleveland Fed nowcast sees October at about 3.75%. EIA expects lower gas prices in 2027, but most prices will keep rising, just more slowly.
Too early“Groceries are driving inflation.”
Food at home is up only 1.8% and accounts for about 4% of the typical household’s extra cost in our calculation; gasoline is 32%.
False“Tariffs are behind the inflation spike.”
Core goods excluding food and energy are up 0.7%; energy is up 20.4%. Tariffs may lift specific items, but they do not explain the headline jump.
Misleading“Wages are falling behind prices.”
Real average hourly earnings fell 0.7% over the year to September 2026 (BLS).
TrueFrequently asked questions
What is the current US inflation rate?
The US inflation rate was 3.7% in the 12 months to September 2026, according to the Bureau of Labor Statistics release of 14 October 2026. Prices rose 0.6% in September alone. Core inflation, excluding food and energy, was 2.6%. The October figure will be published on 10 November 2026.
Why is inflation going up in 2026?
Mainly energy. Gasoline is up 34.2% over the year and the energy index 20.4%, which BLS says drove over half of September’s monthly rise. The EIA links high oil prices to constrained Middle East supply and Strait of Hormuz disruption. Core inflation, at 2.6%, has barely moved since January.
Which prices are rising the fastest right now?
Gasoline (+34.2%), airline fares (+22.4%), utility gas (+5.0%), electricity (+4.4%) and restaurant meals (+3.5%) lead the major categories for the year to September 2026. Fuel oil rose 74.2% but has a tiny weight. Used cars (-1.5%) and car insurance (-5.0%) are getting cheaper.
Is inflation as bad as 2022?
No. Headline inflation peaked at 9.1% in June 2022 and core at 6.6% in September 2022. Today they are 3.7% and 2.6%. The similarity is that gasoline is again the main driver, but this time housing, cars and groceries are rising far more slowly.
How much is inflation costing the average household?
KalQLater estimates about $2,570 a year, or $214 a month, by applying September 2026 CPI changes to average household spending from the BLS Consumer Expenditure Survey. A heavy driver could pay around $3,400 more; a household without a car about $1,750 more.
Are wages keeping up with inflation?
Not currently. Average hourly earnings rose 3.0% in the year to September 2026 while CPI rose 3.7%, so BLS reports real hourly earnings down 0.7%. Wages were beating inflation by more than a point in January 2026 before gasoline surged.
Will the Fed raise rates because of inflation?
The Fed already raised its target range by a quarter point in September 2026, to 3.75%–4.00%, saying inflation remains elevated. Its next decision is on 28 October 2026. With core inflation at 2.6%, the debate is whether energy-driven inflation justifies further hikes.
Will prices go down in 2027?
Gasoline may: the EIA forecasts an average of $3.56 a gallon in 2027, down from $3.91 in 2026. Most other prices are expected to keep rising, but more slowly. Falling inflation means smaller increases, not lower prices overall.
How we built this analysis
- Headline and core 12-month rates calculated from the unadjusted BLS CPI-U indexes (CPIAUCNS and CPILFENS, via FRED): e.g., September 2026 headline = 336.940 / 324.800 - 1 = 3.74%, reported by BLS as 3.7%; core = 339.287 / 330.804 - 1 = 2.56% (2.6%). October 2025 has no published index, so no rate is shown for that month.
- 2022 comparison: June 2022 headline = 296.311 / 271.696 - 1 = 9.06% (9.1%); September 2022 core = 298.442 / 279.884 - 1 = 6.63% (6.6%); September 2022 headline = 296.808 / 274.310 - 1 = 8.2%.
- Real wage growth = 12-month change in average hourly earnings of all private employees (CES0500000003) minus 12-month CPI-U change. September 2026: 37.81 / 36.70 - 1 = 3.02%, minus 3.74% = -0.71 points, consistent with BLS’s published -0.7% real earnings change. BLS’s official real earnings figure deflates by the seasonally adjusted CPI; our monthly series uses the unadjusted CPI, so individual months can differ by about 0.1 point.
- Household cost: 2024 average annual spending per consumer unit from the BLS Consumer Expenditure Survey (released 19 December 2025) multiplied by the matching September 2026 12-month CPI change. Mappings: utilities to energy services (4.6%), public and other transportation to airline fares (22.4%), healthcare to medical care (1.5%), vehicle purchases to new vehicles (0.6%), all remaining consumer categories ($15,794, including other vehicle expenses net of insurance) to core CPI (2.6%). Personal insurance and pensions ($9,797) and cash contributions ($2,292) excluded. Total $2,572 on $66,086 = 3.89%. Heavy driver doubles gasoline to $4,822; non-driver sets it to $0.
- Contribution to headline inflation approximated as relative importance (August 2026) x 12-month change / (1 + change): energy 7.418 x 20.4% / 1.204 = 1.26 points; gasoline 3.853 x 34.2% / 1.342 = 0.98; core 79.075 x 2.6% / 1.026 = 2.00; food 13.507 x 2.5% / 1.025 = 0.33. These are approximations and do not sum exactly to 3.7%.
- Nowcasts (Cleveland Fed) and forecasts (EIA) are labelled as such; survey figures (University of Michigan, NerdWallet/Harris Poll) are self-reported.
Limitations
Our household calculation applies 2026 price changes to 2024 spending levels and average budgets; your mix of spending, region and whether you rent or own can produce a very different personal inflation rate. Several CE categories do not map exactly to a single CPI item (for example, healthcare spending in the CE is largely insurance premiums, and public transportation includes more than airfares). The University of Michigan figure is preliminary; the final October reading is due 23 October 2026. Cleveland Fed nowcasts and EIA forecasts are model estimates that can change quickly with oil prices. We could not open the FDIC national rates page, so we do not quote average savings rates. This article is for information only and is not financial advice.
Spotted an error? See our corrections policy. Read how we work in our methodology and editorial standards.
Sources
- U.S. Bureau of Labor StatisticsConsumer Price Index News Release, September 2026Headline, core and category 12-month and monthly changes; relative importance; next release date
- U.S. Bureau of Labor StatisticsReal Earnings, September 2026Real average hourly earnings -0.7% over the year
- U.S. Bureau of Labor StatisticsThe Employment Situation, September 2026Payrolls +29,000, unemployment 4.2%, average hourly earnings $37.81 (+3.0%)
- U.S. Bureau of Labor StatisticsConsumer Expenditures, 2024 (news release)Average annual household spending by category
- U.S. Bureau of Labor StatisticsConsumer Expenditures in 2024 (report, Table 2)Shelter and utilities spending
- Federal Reserve Bank of St. Louis (FRED), BLS dataCPI for All Urban Consumers: All Items (CPIAUCNS)Monthly index 2021–2026 for headline trend and 2022 peak
- Federal Reserve Bank of St. Louis (FRED), BLS dataCPI: All Items Less Food and Energy (CPILFENS)Monthly core index 2021–2026
- Federal Reserve Bank of St. Louis (FRED), BLS dataAverage Hourly Earnings of All Employees, Total Private (CES0500000003)Monthly wage series for real wage calculation
- Federal Reserve Bank of ClevelandInflation NowcastingOctober 2026 CPI nowcast 3.75% (updated 23 Oct 2026)
- U.S. Energy Information AdministrationShort-Term Energy Outlook, October 2026Brent and gasoline forecasts; Middle East supply constraints
- Board of Governors of the Federal Reserve SystemFOMC statement, 16 September 2026Target range raised to 3.75%–4.00%
- Board of Governors of the Federal Reserve SystemFOMC meeting calendar27–28 October 2026 meeting
- University of MichiganSurveys of ConsumersPreliminary October 2026 sentiment 46.3; inflation expectations 4.7% and 3.5%
- Trading EconomicsUS Consumer Sentiment Falls to Five-Month LowFive-month-low context; current conditions 44.7
- NerdWallet (via Business Wire/Finviz)Nearly 2 in 5 Americans expect to rely on credit as inflation hits 3.7%Consumer Financial Resilience Index, October 2026 (Harris Poll survey)