German Pension Increase 2027 (Rentenerhöhung): How Much More, and What Else Changes?
German pensions are forecast to rise about 4.4% on 1 July 2027, which would add roughly €66 a month gross to a €1,500 pension (about €58 after health and care contributions). That figure is the Deutsche Rentenversicherung’s spring 2026 estimate; the binding rate is set in spring 2027. Separately, Mütterrente III adds half a pension point per child born before 1992 from January 2027, but it is only paid from 2028, with back pay.

The short answer: about 4.4% more from July 2027, but nothing is fixed yet
The best current estimate for the Rentenerhöhung 2027 is 4.4%, from the Deutsche Rentenversicherung’s May 2026 estimate. An older government projection said 4.75%. Either way, it would be the sixth rise in a row above 3.7%, and no official figure will exist until spring 2027.
Pensions in Germany rise every 1 July. In 2026 they went up 4.24%, lifting the aktueller Rentenwert (the euro value of one pension point) from €40.79 to €42.52. The Deutsche Rentenversicherung (DRV) says this was higher than the 3.73% it had expected in December, mainly because wages grew faster in 2025.
For 2027, the latest forecast is the DRV’s Frühjahrsfinanzschätzung 2026 (May 2026): +4.4% on 1 July 2027. The government’s Rentenversicherungsbericht 2025, approved by the cabinet on 19 November 2025, projected 4.75% in its middle scenario. The 2026 edition of that report usually comes out in November and had not been published as of 23 October 2026.
The two headline searches this week, ‘nachzahlung rente’ and ‘mütterrente 3 nachzahlung’, are mostly about Mütterrente III. It applies legally from 1 January 2027, but the DRV says it will only be paid from 2028. Existing pensioners then get the 2027 months as back pay, automatically.
Rentenerhöhung 2027 calculator: your new pension, Mütterrente III and net amount
Enter your current gross monthly pension. The increase defaults to the 4.4% DRV forecast for July 2027; change it to test the 4.75% government projection or the final rate once it is announced in spring 2027. Add children born before 1992 to estimate Mütterrente III, and your health and care rates for an approximate net figure. Estimates only, not financial advice.
- New gross pension (from July 2027)
- 1.566,00 €
- Increase per month / per 12 months
- 66,00 € / 792,00 €
- Increase received in 2027 (Jul–Dec)
- 396,00 €
- Implied Rentenwert 2027
- €44.39
- Approx. net pension now → after increase
- 1.314,75 € → 1.372,60 €
- Net increase per month
- 57,85 €
Estimate, not financial advice. Deductions used: 12.35% (health 7.3% + half the Zusatzbeitrag + care). Mütterrente III is paid from 2028 with back pay. Income tax is not modelled.
How much will pensions rise in July 2027? Rentenanpassung 2027 forecasts compared
Two official-source forecasts exist: 4.4% (DRV, May 2026) and 4.75% (government Rentenversicherungsbericht, November 2025). At 4.4%, the Rentenwert would rise from €42.52 to about €44.39. The newer DRV estimate is the better guide because it uses more recent wage data.
| Source | Published | 2027 increase | Rentenwert implied* | Status |
|---|---|---|---|---|
| Deutsche Rentenversicherung, Frühjahrsfinanzschätzung 2026 | May 2026 | 4.4% | €44.39 | Forecast |
| Bundesregierung, Rentenversicherungsbericht 2025 (middle variant) | 19 Nov 2025 | 4.75% | €44.54 | Projection |
| Rentenversicherungsbericht 2026 | Expected Nov 2026 | Not yet published | n/a | Pending |
| BMAS Rentenwertbestimmungsverordnung 2027 | Spring 2027 | Not yet set | n/a | Binding figure |
*KalQLater applied each percentage to today’s €42.52. The 2025 report itself printed €44.32 for 2027 because it started from an older 2026 estimate; the real 2026 value turned out higher.
Why the gap? The formula follows gross wage growth in the previous year, adjusted for changes in contribution rates and the ratio of pensioners to contributors. For 2026, wages pushed the rise to 4.05%, and the 48% Haltelinie lifted it to 4.24%, the DRV explains. Wage data for all of 2026 only arrives in early 2027, which is why nobody can fix the 2027 rate yet.
The same DRV estimate expects much smaller increases after that: 2.3% in 2028, 2.8% in 2029 and 2.9% in 2030. The government report put the average yearly rise to 2039 at about 2.8%.
Rentenerhöhung history: how big were past increases?
From 2015 to 2026, the West German pension increase ranged from 0% (2021) to 5.35% (2022). Since 2022, every increase has been above 3.7%. A 4.4% rise in 2027 would be in line with that recent run, not a break from it.
German pension increase each 1 July, 2015–2027 (West / unified, %)
Source: Deutsche Rentenversicherung; Rentenwert table (sozialversicherung-kompetent.de); 2027 = DRV forecast, May 2026View the data
| Label | Value |
|---|---|
| 2015 | 2.10% |
| 2016 | 4.25% |
| 2017 | 1.90% |
| 2018 | 3.22% |
| 2019 | 3.18% |
| 2020 | 3.45% |
| 2021 | 0.00% |
| 2022 | 5.35% |
| 2023 | 4.39% |
| 2024 | 4.57% |
| 2025 | 3.74% |
| 2026 | 4.24% |
| 2027 (proj.) | 4.40% |
| 1 July | Rentenwert West | Rentenwert Ost | Increase West |
|---|---|---|---|
| 2015 | €29.21 | €27.05 | 2.10% |
| 2016 | €30.45 | €28.66 | 4.25% |
| 2017 | €31.03 | €29.69 | 1.90% |
| 2018 | €32.03 | €30.69 | 3.22% |
| 2019 | €33.05 | €31.89 | 3.18% |
| 2020 | €34.19 | €33.23 | 3.45% |
| 2021 | €34.19 | €33.47 | 0.00% |
| 2022 | €36.02 | €35.52 | 5.35% |
| 2023 | €37.60 | €37.60 (unified) | 4.39% |
| 2024 | €39.32 | €39.32 | 4.57% |
| 2025 | €40.79 | €40.79 | 3.74% |
| 2026 | €42.52 | €42.52 | 4.24% |
| 2027 (forecast) | ≈€44.39 | ≈€44.39 | ≈4.4% |
Aktueller Rentenwert, West / unified (€ per pension point), 2015–2027
Source: Deutsche Rentenversicherung; sozialversicherung-kompetent.de; 2027 = KalQLater calculation at 4.4% forecastView the data
| Label | Value |
|---|---|
| 2015 | €29.21 |
| 2016 | €30.45 |
| 2017 | €31.03 |
| 2018 | €32.03 |
| 2019 | €33.05 |
| 2020 | €34.19 |
| 2021 | €34.19 |
| 2022 | €36.02 |
| 2023 | €37.60 |
| 2024 | €39.32 |
| 2025 | €40.79 |
| 2026 | €42.52 |
| 2027 (proj.) | €44.39 |
Did German pensions keep up with inflation?
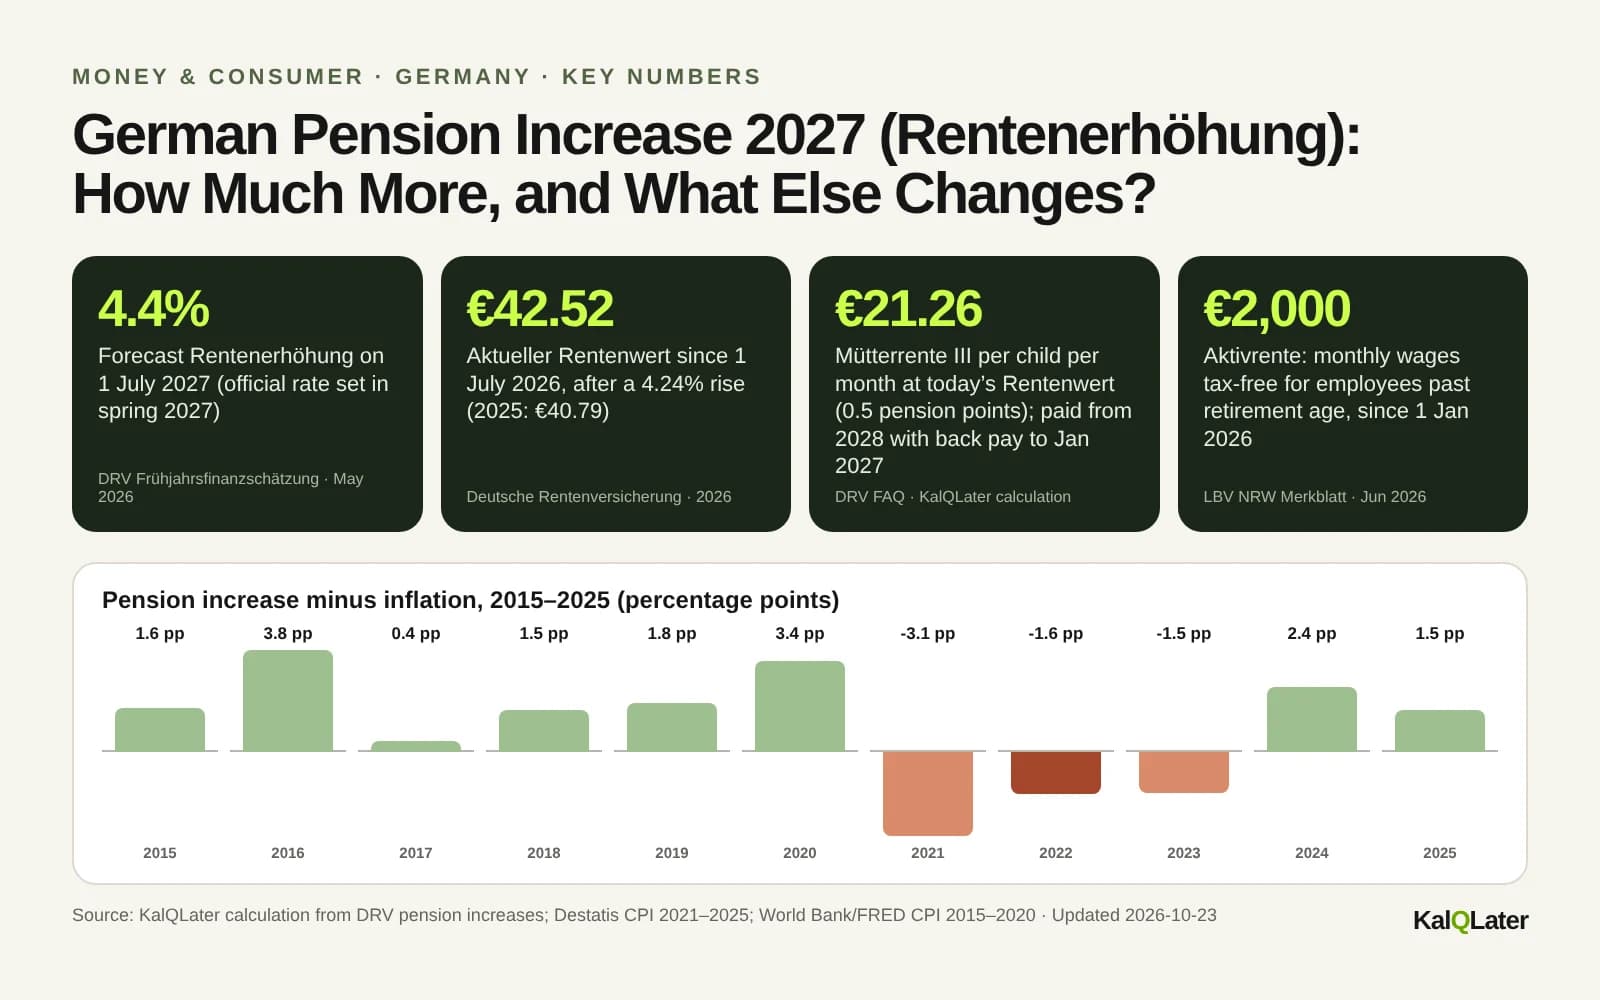
Over the long run, yes: the Rentenwert rose 42.6% between July 2014 and July 2025, while consumer prices rose about 29% over 2015–2025. But pensioners lost ground in 2021, 2022 and 2023, when inflation beat the pension increase each year.
Pension increase minus inflation, 2015–2025 (percentage points)
Source: KalQLater calculation from DRV pension increases; Destatis CPI 2021–2025; World Bank/FRED CPI 2015–2020View the data
| Label | Value |
|---|---|
| 2015 | 1.6 pp |
| 2016 | 3.8 pp |
| 2017 | 0.4 pp |
| 2018 | 1.5 pp |
| 2019 | 1.8 pp |
| 2020 | 3.4 pp |
| 2021 | -3.1 pp |
| 2022 | -1.6 pp |
| 2023 | -1.5 pp |
| 2024 | 2.4 pp |
| 2025 | 1.5 pp |
Annual inflation (Destatis CPI) was 3.1% in 2021, 6.9% in 2022 and 5.9% in 2023, before easing to 2.2% in both 2024 and 2025. The 2021 zero round hurt most: West German pensions did not rise at all while prices climbed 3.1%.
Inflation is picking up again. Destatis confirmed 3.3% in September 2026, driven by energy prices (+14.9% year on year), while core inflation was 2.4%. If prices keep rising at around 3%, a 4.4% increase in July 2027 would still leave a real gain, but a much thinner one than the headline suggests, and less after deductions.
Rentenerhöhung 2027 table: how much more on a €1,000, €1,500 or €2,000 pension?
At the 4.4% forecast, a €1,500 gross pension rises by €66 a month (€792 a year), or about €57.85 net after average health and care contributions. A €1,000 pension gains €44 gross and a €2,000 pension €88 gross per month.
| Gross pension now | New gross pension | Extra gross / month | Extra gross / 12 months | Extra net / month (parent)* | Extra net / month (childless)** |
|---|---|---|---|---|---|
| €1,000 | €1,044 | €44.00 | €528 | €38.57 | €38.17 |
| €1,500 | €1,566 | €66.00 | €792 | €57.85 | €57.26 |
| €2,000 | €2,088 | €88.00 | €1,056 | €77.13 | €76.34 |
*Parent: 7.3% health + 1.45% (half of the 2.9% average Zusatzbeitrag) + 3.6% care = 12.35% deducted. Childless: same health share plus 4.5% care, the planned 2027 rate under a bill approved by the cabinet on 30 September 2026 (4.2% today) = 13.25%**. Income tax may take a further slice; see the tax section below.
Extra gross pension per month in 2027: 4.4% forecast vs 4.75% projection
Source: KalQLater calculation from DRV (4.4%) and Rentenversicherungsbericht 2025 (4.75%) forecastsView the data
| Label | Value |
|---|---|
| €1,000 at 4.4% | €44.00 |
| €1,000 at 4.75% | €47.50 |
| €1,500 at 4.4% | €66.00 |
| €1,500 at 4.75% | €71.25 |
| €2,000 at 4.4% | €88.00 |
| €2,000 at 4.75% | €95.00 |
Mütterrente III 2027: how much per child, and when does the Nachzahlung come?
Mütterrente III credits half a pension point more per child born before 1992, worth €21.26 a month at today’s Rentenwert. It applies from 1 January 2027, but the DRV will only start paying it in 2028. Pensioners already retired then receive the 2027–2028 months as automatic back pay.
Until now, parents got up to 30 months of child-raising credit (Kindererziehungszeit) for a child born before 1992, versus 36 months for later children. Mütterrente III closes that gap: six extra months = 0.5 Entgeltpunkte (pension points) per child, so each child can count up to 3 points in total. The DRV estimates about 10 million pensioners could benefit. Fathers can qualify too if the credit was assigned to them.
| Period | Rentenwert | Per child / month | Per child / 12 months | 2 children / month |
|---|---|---|---|---|
| Jan–Jun 2027 (known) | €42.52 | €21.26 | €255.12 | €42.52 |
| Jul 2027 onward at 4.4% forecast | ≈€44.39 | ≈€22.20 | ≈€266.34 | ≈€44.39 |
| Back pay for all of 2027 (forecast) | mixed | n/a | ≈€260.73 | ≈€521.46 |
The DRV’s own FAQ (January 2026) gives the value of half a point as €20.40, which was the Rentenwert before July 2026. After the 4.24% increase it is €21.26. Back pay for 2027 = 6 × €21.26 + 6 × ≈€22.20 ≈ €260.73 per child, before health and care contributions. Months in 2028 before the first regular payment would be added to that.
- No application needed for current pensioners Anyone whose pension starts before 1 January 2028 gets the recalculation and Nachzahlung automatically, according to the DRV.
- Future pensioners If child-raising periods are already on your record, the DRV checks the new rule automatically in 2028. If not, it is checked when you apply for your pension.
- It can reduce other benefits As part of the statutory pension, Mütterrente III can be counted against Grundsicherung, Wohngeld or a survivor’s pension.
- Exact payment date As of 23 October 2026, the DRV says only ‘from 2028’. No month has been announced.
What will be deducted from my pension in 2027?
Statutory-insured pensioners pay 7.3% health contribution plus half their fund’s Zusatzbeitrag, plus the full 3.6% care contribution (4.2% if childless). For childless pensioners, a cabinet bill would raise care to 4.5% from January 2027, eating part of the July increase.
Health insurance (Krankenversicherung der Rentner) costs 14.6% of the gross pension plus the fund’s Zusatzbeitrag. The DRV pays half of both, the pensioner the other half. Care insurance (Pflegeversicherung) is 3.6%, and pensioners pay it in full, with no share from the DRV. Childless pensioners pay a 0.6-point surcharge, for 4.2%.
The official average Zusatzbeitrag was 2.5% in 2025 and 2.9% in 2026. Funds set their own rates, so your deduction may be higher or lower. The 2027 average is due from the health ministry by 1 November; see our Zusatzbeitrag 2027 analysis for the forecast and fund-by-fund rates.
The care reform (Pflegeneuordnungsgesetz) approved by the cabinet on 30 September 2026 would raise the childless surcharge from 0.6% to 0.9% from 1 January 2027, taking the total to 4.5%. It is still a bill. On a €1,500 pension that would mean €4.50 a month more in deductions from January, six months before the pension increase arrives.
Will the 2027 pension increase be taxed? Besteuerungsanteil explained
Yes: the whole increase is taxable, because your tax-free pension amount is frozen in euros after your first full year of retirement. New retirees in 2027 pay tax on 84.5% of their pension, up from 84% for 2026 starters. Whether tax is actually due depends on total income versus the Grundfreibetrag.
| Pension starts in | Taxable share |
|---|---|
| 2005 or earlier | 50% |
| 2020 | 80% |
| 2023 | 82.5% |
| 2024 | 83% |
| 2025 | 83.5% |
| 2026 | 84% |
| 2027 | 84.5% |
| 2058 | 100% |
The tax-free part (Rentenfreibetrag) is fixed as a euro amount based on the pension in the year after retirement starts. Every later Rentenerhöhung is therefore 100% taxable. That is why a pension that was tax-free years ago can slowly cross into tax territory.
The Grundfreibetrag (basic allowance) is €12,348 in 2026 for a single person. According to Sachsen-Anhalt’s finance ministry, a single pensioner with only a statutory pension and a 2026 start pays no income tax up to about €17,084 gross a year; for a 2005 start the threshold is about €20,295. Pensioners can deduct a €102 flat allowance for expenses and €36 for special expenses, and health and care contributions are deductible.
Aktivrente: can working pensioners really earn €2,000 a month tax-free?
Yes, if you are an employee who has reached the regular retirement age: since 1 January 2026, up to €2,000 a month of wages (€24,000 a year) is income-tax-free. Social contributions are still due, mini-jobs are excluded, and self-employed people do not qualify.
The Aktivrente (§ 3 Nr. 21 EStG) was approved by the Bundesrat on 19 December 2025 and applies from 1 January 2026, according to the tax office of North Rhine-Westphalia (LBV NRW). It starts in the month after you reach the Regelaltersgrenze, there is no minimum or maximum working time, and you do not need to draw a pension to use it.
- Who qualifies Employees past the regular retirement age whose employer pays pension contributions on their wages. Mini-jobs are excluded; Sachsen-Anhalt’s finance ministry says self-employed people and civil servants are not covered.
- What stays The allowance is tax only: the wages remain subject to social insurance.
- How it works It is applied automatically through payroll tax (no application). If the job is taxed under class VI, you must confirm to the employer that you do not use the allowance elsewhere.
- Example A 68-year-old earning €1,800 gross a month part-time pays no income tax on that wage under the Aktivrente. On €2,500 a month, €500 would be taxable. The pension itself is taxed as normal.
Rentenpaket 2025: is the 48% pension level guaranteed?
The Rentenpaket 2025 keeps the Rentenniveau at 48% up to and including the 1 July 2031 adjustment. It passed the Bundesrat on 19 December 2025. Contributions stay at 18.6% through 2027 but are projected to jump to 19.8% in 2028.
The Rentenniveau compares a standard pension with average earnings, both after social contributions and before tax. The Haltelinie stops it falling below 48%. In 2026 it mattered: without it, pensions would have risen 4.05% instead of 4.24%, the DRV says. The government must report in 2029 on what happens after 2031; its own projection has the level falling to 46.3% by 2039.
The bill comes later. The government projects the contribution rate rising from 18.6% (through 2027) to 19.8% in 2028 and 20% in 2029. That matters for 2028 pensions too: higher contribution rates reduce the increase through the formula.
What should pensioners and their families do now?
Do not budget on a fixed 2027 figure: plan with about 4% and treat anything higher as a bonus. Check your Krankenkasse’s 2027 Zusatzbeitrag, confirm your child-raising periods are on record, and keep 2028 Mütterrente III back pay out of your plans for 2027.
- 1Plan with a conservative figure
Use 4% to 4.4% for July 2027 in your budget. The official rate comes in spring 2027; update the calculator above when it does.
- 2Watch your Krankenkasse letter
If your fund raises its Zusatzbeitrag for 2027, you can switch. The DRV page says a fund that introduces or raises the Zusatzbeitrag gives you a special right to cancel.
- 3Check child-raising periods
Parents of children born before 1992 who are not yet retired should check their Versicherungsverlauf (insurance record). Existing pensioners need not apply for Mütterrente III.
- 4Do not spend the Nachzahlung early
Mütterrente III back pay arrives in 2028, not 2027. Watch for scam calls or letters asking you to ‘apply’ or pay a fee: the DRV says it is automatic.
- 5Check your tax position
If your total pension income is near €17,000 a year (single), the July increase may push you into paying tax. A Lohnsteuerhilfeverein or tax adviser can check.
- 6Working past retirement age?
Ask your employer’s payroll whether the €2,000 Aktivrente allowance is applied.
- 7Helping parents from abroad?
Questions about a parent’s pension, child-raising periods or deductions can go to the free DRV service line on 0800 1000 4800 (Mon–Thu 08:00–19:00, Fri 08:00–15:30).
Claims vs evidence: Rentenerhöhung 2027 headlines
“Pensions will rise 5% in 2027.”
The DRV’s May 2026 forecast is 4.4%; the government’s November 2025 projection was 4.75%. No official source says 5%.
Misleading“The 2027 increase is already fixed.”
The rate is set by ordinance in spring 2027 from wage data not complete until early 2027. All figures today are forecasts.
False“Mothers get the Mütterrente III Nachzahlung in 2027.”
The rule applies from 1 January 2027, but the DRV says payment starts only in 2028, with back pay for earlier months.
False“Pensioners can earn €2,000 a month tax-free with the Aktivrente.”
True for employees past the regular retirement age with social-insurance jobs. Mini-jobs and the self-employed are excluded, and social contributions still apply.
Partly true“The 48% Rentenniveau is now guaranteed.”
Only up to the 1 July 2031 adjustment. The government projects 46.3% by 2039 without further reform.
Partly true“Pension increases beat inflation.”
Over 2015–2025 the Rentenwert rose 42.6% vs about 29% CPI, but pensions lost ground in 2021, 2022 and 2023.
Partly trueFrequently asked questions
How much will pensions increase in July 2027?
The latest forecast, from the Deutsche Rentenversicherung’s spring 2026 estimate, is 4.4% on 1 July 2027. The government’s 2025 pension report projected 4.75%. The official rate is set in spring 2027, so as of 23 October 2026 neither figure is final.
What will the aktueller Rentenwert be in 2027?
It is €42.52 since 1 July 2026. At the 4.4% forecast it would be about €44.39 from 1 July 2027, and about €44.54 at 4.75%. These are KalQLater calculations from forecasts; the official value comes with the spring 2027 ordinance.
How much is Mütterrente III per child?
Half a pension point per child born before 1992. At today’s Rentenwert of €42.52 that is €21.26 gross a month, or €255.12 a year. From July 2027 it would be about €22.20 a month if pensions rise 4.4%.
When will the Mütterrente III Nachzahlung be paid?
The DRV says Mütterrente III will be paid from 2028 because of the technical work involved. Pensioners retired before January 2028 get back pay automatically from January 2027. At forecast values, back pay for 2027 alone is about €261 gross per child.
Do I need to apply for Mütterrente III?
No, if you already receive a pension before 1 January 2028: the DRV recalculates it automatically. If you are not yet retired, it is checked in 2028 or when you apply for your pension. No separate application is needed.
How much is deducted from a German pension for health and care?
Statutory-insured pensioners pay 7.3% plus half their fund’s Zusatzbeitrag for health (8.75% at the 2.9% average) and 3.6% for care, or 4.2% if childless. That is about 12.35% for a parent. A bill would raise the childless care rate to 4.5% in 2027.
Is the Aktivrente €2,000 a month tax-free?
Yes. Since 1 January 2026, employees who have reached the regular retirement age can earn up to €2,000 a month from a job subject to pension contributions without income tax. Mini-jobs and self-employment do not qualify, and social contributions remain.
Do I pay tax on my pension increase?
Yes, in full. The tax-free part of your pension is fixed in euros after your first full year, so every later increase is taxable. New 2027 retirees pay tax on 84.5% of their pension. Tax is only due if total income exceeds allowances such as the €12,348 Grundfreibetrag (2026).
How we built this analysis
- Pension increases and Rentenwerte for 2015–2026 come from the Deutsche Rentenversicherung (2026 press release and FAQ) and a compiled Rentenwert table (sozialversicherung-kompetent.de) that matches DRV figures. Rates are West German until 2023, nationwide since July 2023.
- 2027 forecast: 4.4% from the DRV Frühjahrsfinanzschätzung 2026 (May 2026) and 4.75% from the Rentenversicherungsbericht 2025 (Bundestag Drucksache 21/3080, middle variant), both as cited by rechner-hub.de and matched by vermoegenszentrum.de. Implied Rentenwert = €42.52 × (1 + rate), rounded to cents: €44.39 at 4.4%, €44.54 at 4.75%.
- Worked examples: extra gross = pension × 4.4% (e.g., €1,500 × 0.044 = €66.00; × 12 = €792). Net = gross × (1 − deduction rate). Parent: 7.3% + 2.9%/2 + 3.6% = 12.35%, so €66 × 0.8765 = €57.85. Childless (2027 plan): 7.3% + 1.45% + 4.5% = 13.25%, so €66 × 0.8675 = €57.26.
- Mütterrente III: 0.5 Entgeltpunkte × Rentenwert. €42.52 × 0.5 = €21.26; €44.39 × 0.5 = €22.195 (≈€22.20). 2027 back pay per child = 6 × €21.26 + 6 × €22.195 = €260.73.
- Pension vs inflation: July pension increase minus annual average CPI (Destatis for 2021–2025; World Bank series via FRED for 2015–2020, rounded to one decimal). Cumulative: €40.79/€28.61 − 1 = 42.6% vs compounded CPI 2015–2025 = 29.0%.
- All figures as of 23 October 2026. Forecasts are labelled; the binding 2027 rate will replace them when published.
Limitations
The 2027 increase is a forecast; it could end up higher or lower depending on 2026 wages, contribution rates and the pensioner ratio. Net figures use average rates and ignore income tax, individual Zusatzbeitrag, private insurance and Beihilfe cases, and rounding of individual deductions. Mütterrente III amounts are gross and before any offset against Grundsicherung, Wohngeld or survivor’s pensions; the exact 2028 payment date is not yet known. The childless care rate of 4.5% depends on a bill still in parliament. This article is general information, not financial, tax or legal advice; check your own Rentenbescheid or ask the Deutsche Rentenversicherung.
Spotted an error? See our corrections policy. Read how we work in our methodology and editorial standards.
Sources
- Deutsche RentenversicherungRentenanpassung 2026: Renten steigen im Juli um 4,24 Prozent4.24% increase, Rentenwert €40.79 → €42.52, December forecast 3.73%, 48% Haltelinie
- Deutsche RentenversicherungFAQ: Rentenanpassung 20264.05% without Haltelinie, formula factors, notice timing
- Deutsche RentenversicherungFAQ: Mütterrente III0.5 points per child, from 1 Jan 2027, paid from 2028, back pay, no application, ~10 million (Stand 16 Jan 2026)
- Deutsche RentenversicherungKranken- und Pflegeversicherung der Rentner7.3% + half Zusatzbeitrag, 3.6% care paid in full, 4.2% childless, subsidy for privately insured
- Die BundesregierungRentenpaket 2025: Damit die Rente stabil, verlässlich und gerecht bleibt48% to 2031, Bundesrat 19 Dec 2025, Mütterrente III retroactive payment
- Die BundesregierungRentenversicherungsbericht 2025: Ausblick auf die Entwicklung der RentenCabinet 19 Nov 2025; contribution rate 18.6% to 2027, 19.8% in 2028; ~2.8% average rise; 46.3% by 2039
- Statistisches Bundesamt (Destatis)Pressemitteilung Nr. 364 vom 13. Oktober 2026: Inflationsrate September 20263.3% CPI, core 2.4%, energy +14.9%
- Statistisches Bundesamt (Destatis)Verbraucherpreisindex für Deutschland (Jahreswerte)Annual CPI 2021–2025
- Federal Reserve Bank of St. Louis (FRED) / World BankInflation, consumer prices for GermanyAnnual CPI 2015–2020
- Landesamt für Besoldung und Versorgung NRWMerkblatt Aktivrentengesetz (Stand Juni 2026)€2,000/month, § 3 Nr. 21 EStG, from 1 Jan 2026, mini-jobs excluded, social insurance remains
- Ministerium der Finanzen Sachsen-AnhaltRentenbroschüre 2026 (Rechtsstand Juni 2026)Besteuerungsanteil table, Grundfreibetrag €12,348, tax-free pension thresholds, Aktivrente scope
- Techniker KrankenkasseDer gesetzlich festgelegte Zusatzbeitragssatz 2025 und 2026Average Zusatzbeitrag 2.5% (2025), 2.9% (2026)
- sozialversicherung-kompetent.deDer aktuelle Rentenwert nach § 68 SGB VIRentenwert West/Ost history 2014–2026
- rechner-hub.de / vermoegenszentrum.deRentenerhöhung 2027: 4,75 % oder 4,4 %? Was wirklich giltCites DRV Frühjahrsfinanzschätzung 2026 (4.4%; 2.3%/2.8%/2.9% for 2028–30) and Rentenversicherungsbericht 2025 Übersicht B 3.6 (4.75%)
- leinetal24 (Ippen Media)Pflegeversicherung 2027: Kinderlose zahlen höheren BeitragssatzChildless surcharge 0.6% → 0.9% planned; cabinet 30 Sep 2026 (2 Oct 2026)